
Renouncing one’s citizenship for Americans residing overseas is not an easy task. People decide to do this either because they have settled permanently in another country or simply because they wish to avoid US tax filing obligations.
No matter the motivation behind the decision, relinquishing US citizenship entails far more than just surrendering one’s passport.
The immigration process and the tax process are connected, but they are not the same thing. Completing a formal renunciation with the U.S. Department of State does not automatically clear outstanding U.S. tax obligations. Former citizens may still need to file tax returns, complete Form 8854, report foreign financial assets, and determine whether the U.S. expatriation tax rules apply.
For Americans living in Switzerland, there is another layer to consider: U.S. expatriation planning needs to be coordinated with the individual’s tax declaration requirements in Switzerland.
Understanding these obligations before starting the renunciation process can help prevent costly mistakes.
What Does Renouncing US Citizenship Involve?
Renunciation is the formal process of giving up U.S. nationality.
Under U.S. law, an individual generally needs to appear personally before a U.S. diplomatic or consular officer outside the United States and formally renounce nationality. The U.S. Department of State explains that the loss of nationality tax declaration switzerland becomes effective once the Department approves a Certificate of Loss of Nationality, commonly known as a CLN.
This is an important distinction.
Renunciation is not simply a tax election, and it cannot normally be completed by sending a letter or form to the IRS.
Once a Certificate of Loss of Nationality is approved, the loss of U.S. nationality is generally irrevocable except through limited administrative or judicial procedures.
Before proceeding, individuals should therefore think carefully about issues such as:
- future travel to and residence in the United States;
- nationality in another country;
- estate and inheritance planning;
- retirement accounts;
- investment portfolios;
- U.S. property ownership; and
- ongoing tax responsibilities.
The tax review should ideally begin before the actual expatriation date.
Tax Obligations Before Renouncing US Citizenship
One of the most important parts of expatriation planning is reviewing your previous U.S. tax compliance.
For tax purposes, individuals who expatriate may need to demonstrate that they complied with their U.S. federal tax obligations for the five tax years preceding expatriation.
This requirement is especially significant because failure to certify five years of compliance on Form 8854 can cause an individual to be classified as a covered expatriate, nevertheless of income or net worth.
Before renouncing, it is therefore sensible to review whether all required filings have been completed correctly.
Depending on individual circumstances, this may include:
- Form 1040 U.S. individual income tax returns;
- foreign bank account reporting;
- foreign financial asset disclosures;
- foreign corporation or partnership reporting;
- trust-related reporting;
- investment income;
- foreign pension reporting; and
- self-employment or business income.
Missing returns should not simply be ignored because citizenship is being surrendered. The renunciation itself does not erase previous tax obligations.
Understanding the US Expatriation Tax
The U.S. expatriation tax is commonly called the exit tax.
However, not everyone who renounces citizenship has to pay it.
Under Internal Revenue Code Section 877A, covered expatriates may be subject to a mark-to-market regime. In simple terms, certain assets are treated as though they were sold for their fair market value on the day before expatriation.
The resulting unrealized gain can then become taxable, subject to applicable exclusions and special rules.
For 2026, the IRS states that the amount of gain otherwise included under the mark-to-market rules is reduced by $910,000.
This does not mean every expatriate receives a $910,000 tax deduction against all income.
The exclusion applies specifically within the Section 877A mark-to-market calculation. Certain items, such as some deferred compensation arrangements, specified tax-deferred accounts, and interests in nongrantor trusts, are subject to separate expatriation rules rather than the standard deemed-sale treatment.
Because of these distinctions, determining the potential exit tax generally requires an asset-by-asset review.
Who May Be Subject to the Exit Tax?
A person who expatriates in 2026 may be classified as a covered expatriate if one or more statutory tests apply.
1. The Tax Liability Test
For expatriations occurring in 2026, the IRS states that a person may meet the covered-expatriate test if their average annual net U.S. income tax liability for the five tax years before expatriation exceeds $211,000.
Importantly, this test looks at tax liability, not simply gross income.
2. The Net-Worth Test
An individual can also become a covered settler if their net worth is $2 million or more on the expatriation date.
Calculating net worth may require valuations of assets such as:
- property;
- investment portfolios;
- business interests;
- pension rights;
- cash and bank accounts; and
- other financial assets.
Liabilities are also relevant to the calculation.
3. The Tax Compliance Test
The third test often surprises people.
Even someone with relatively modest income and a net worth below $2 million can potentially become a covered expatriate if they cannot certify compliance with U.S. federal tax obligations for the five preceding tax years on Form 8854.
There are limited exceptions for certain dual citizens from birth and certain minors, but these rules contain specific conditions and should not be assumed to apply automatically.
Form 8854 and Expatriation Reporting Requirements
Form 8854, Initial and Annual Expatriation Statement, is central to the tax side of renunciation.
The IRS uses this form to collect information about an expatriate’s tax compliance, assets, liabilities, income, and potential covered-expatriate status.
Individuals expatriating under the modern Section 877A regime generally use Form 8854 to certify that they complied with federal tax obligations for the five years before expatriation.
The form can include detailed information on:
- citizenship and residency history;
- prior tax compliance;
- net worth;
- assets and liabilities;
- deferred compensation;
- trusts; and
- property potentially subject to the mark-to-market tax.
The IRS instructions generally require the initial Form 8854 to be attached to the federal income tax return for the year containing the expatriation date.
Failing to file Form 8854 when needed can carry serious consequences. The IRS states that a penalty of $10,000 may apply for certain failures to file the form or provide required information, unless an exception such as reasonable cause applies.
Final US Tax Return After Renunciation
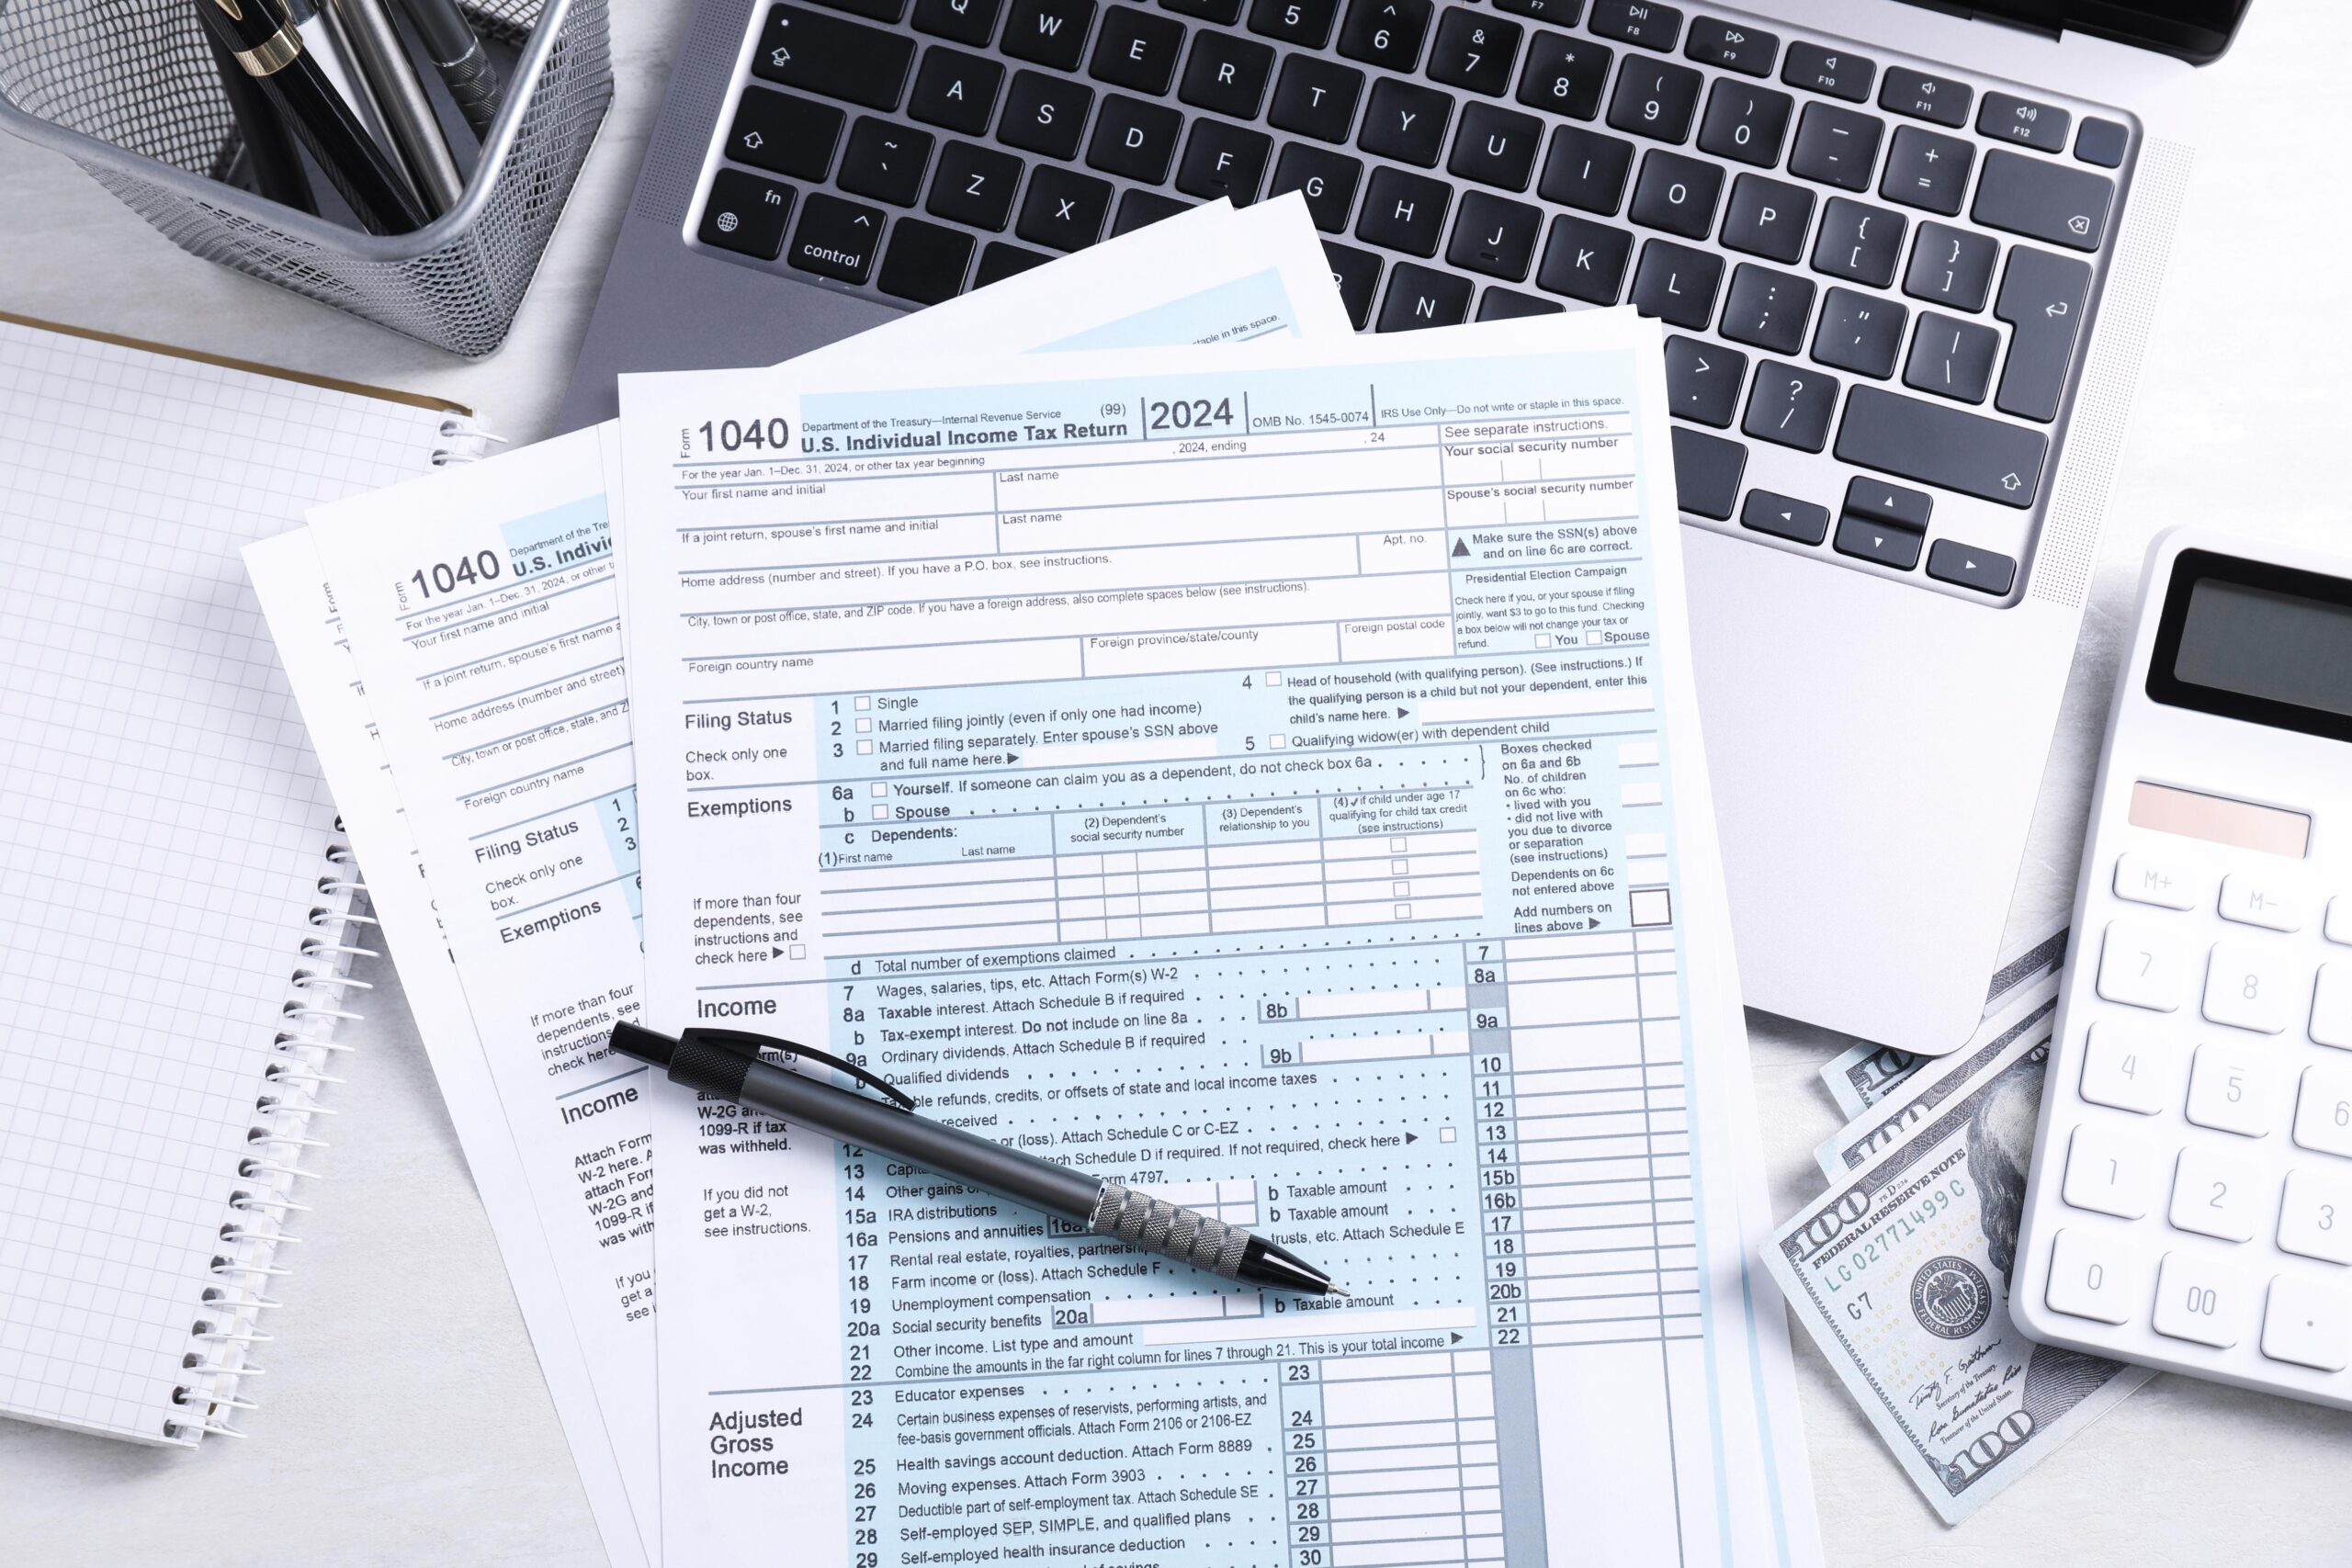
Renouncing during the year can make the final U.S. tax return more complicated than a standard annual filing.
An individual’s U.S. tax status can change on the expatriation date, meaning the year may involve different reporting periods.
The appropriate return could involve Form 1040, Form 1040-NR, or filing rules that reflect the individual’s status during different parts of the year.
The exact treatment depends on the person’s circumstances and expatriation date.
Form 8854 must also be coordinated with the final return.
This is another reason why renunciation should ideally be planned before the consular appointment rather than dealing with tax consequences afterward.
Doing the calculations in advance can reveal whether restructuring assets, correcting previous returns, obtaining valuations, or collecting missing records may be necessary.
Covered Expatriate Rules and Net-Worth Considerations
Being classified as a covered expatriate can have consequences beyond the immediate exit-tax calculation.
For example, special rules can apply to gifts or bequests made by covered expatriates to U.S. citizens or residents.
The IRS has also implemented Section 2801 reporting rules dealing with certain covered gifts and bequests received from covered expatriates.
This means expatriation planning may need to consider not just the individual giving up citizenship but also future estate and family wealth transfers.
Accurate valuations are therefore important.
Someone who believes their net worth is slightly below $2 million should not rely on rough estimates, particularly where they own property, a private company, investment portfolios, pension rights, or other assets whose value may not be immediately obvious.
Foreign Assets, Investments and Income After Renunciation
Giving up U.S. citizenship generally changes future U.S. tax obligations, but it does not mean that assets become tax-free.
After expatriation, former citizens may still have U.S. tax exposure from certain U.S.-source income or U.S. investments.
For people living in Switzerland, Swiss tax responsibilities also remain relevant.
For example, Zurich’s tax guidance states that taxpayers generally need to declare worldwide income and worldwide assets on the applicable Swiss tax return, even where certain foreign items are not directly taxed in Switzerland but may influence the applicable tax rate.
This makes coordination particularly important.
A Swiss resident who is renouncing US citizenship may have:
- Swiss bank accounts;
- U.S. brokerage accounts;
- American retirement plans;
- Swiss pension assets;
- U.S. property;
- Swiss property;
- foreign investment funds; or
- income arising in multiple jurisdictions.
These items should be reviewed from both U.S. and Swiss perspectives.
Completing a U.S. expatriation filing does not replace the person’s tax declaration Switzerland obligations.
Common Tax and Compliance Mistakes to Avoid
One of the most significant errors involves assuming that the Department of State’s renunciation procedure automatically takes care of any U.S. tax considerations.
It doesn’t.
Other frequent errors involve neglecting to file Form 8854, neglecting prior-year filing requirements, underestimating net worth, failing to account for foreign accounts or investments, and assuming no exit tax liability when failing to perform covered expatriate tests.
Another mistake is waiting until after renunciation to begin reviewing tax records.
Ideally, individuals should assemble documentation for at least the previous five tax years before completing expatriation.
Useful records can include:
- previous U.S. tax returns;
- foreign account information;
- investment statements;
- pension statements;
- property valuations;
- company ownership records;
- documentation of liabilities; and
- Swiss tax returns.
People who have not previously complied with U.S. filing obligations should also obtain professional advice before making corrections. The IRS maintains specific relief procedures for some former citizens who meet the applicable eligibility requirements, although these procedures do not apply to everyone.
Professional Tax Guidance for Citizenship Renunciation
The decision to renounce may appear straightforward when viewed only from an immigration perspective.
From a tax perspective, however, the timing can matter considerably.
Professional advice is available in determining whether one qualifies as a covered expatriate, computing net worth, looking into past compliance issues, evaluating mark-to-market gain, preparing form 8854, and filing the last U.S. tax return.
For Swiss residents, it can be equally important to coordinate U.S. expatriation advice with Swiss tax planning.
Switzerland and the United States have extensive cross-border financial reporting arrangements, including FATCA-related information exchange. Swiss authorities explain that FATCA requires relevant foreign financial institutions to disclose information concerning U.S.-linked accounts under the applicable framework.
Professional guidance is particularly valuable when an individual owns businesses, trusts, significant investment portfolios, real estate, pensions, or assets located in several countries.
Conclusion
Renouncing US citizenship is both a legal and a tax process, and completing one does not automatically complete the other.
Before expatriating, individuals should review the previous five years of U.S. tax compliance, determine whether they may be considered a covered expatriate, assess potential exit-tax exposure, and understand the requirements surrounding Form 8854 and the final U.S. tax return.
For Americans living in Switzerland, the planning should also take account of ongoing tax declaration Switzerland requirements, including the reporting of relevant worldwide income and assets.
There is no single expatriation strategy that works for everyone. Income, net worth, investments, pensions, business ownership, family circumstances, and country of residence can all change the outcome.
That is why the best time to understand the tax consequences is before completing the renunciation process. Careful preparation and professional cross-border tax guidance can help ensure that citizenship is relinquished with the necessary filings completed accurately and with fewer unexpected tax consequences.
About The Author